5 Things the Working Class Thinks Are Assets but Are Liabilities, and How to Tell the Real Ones Apart
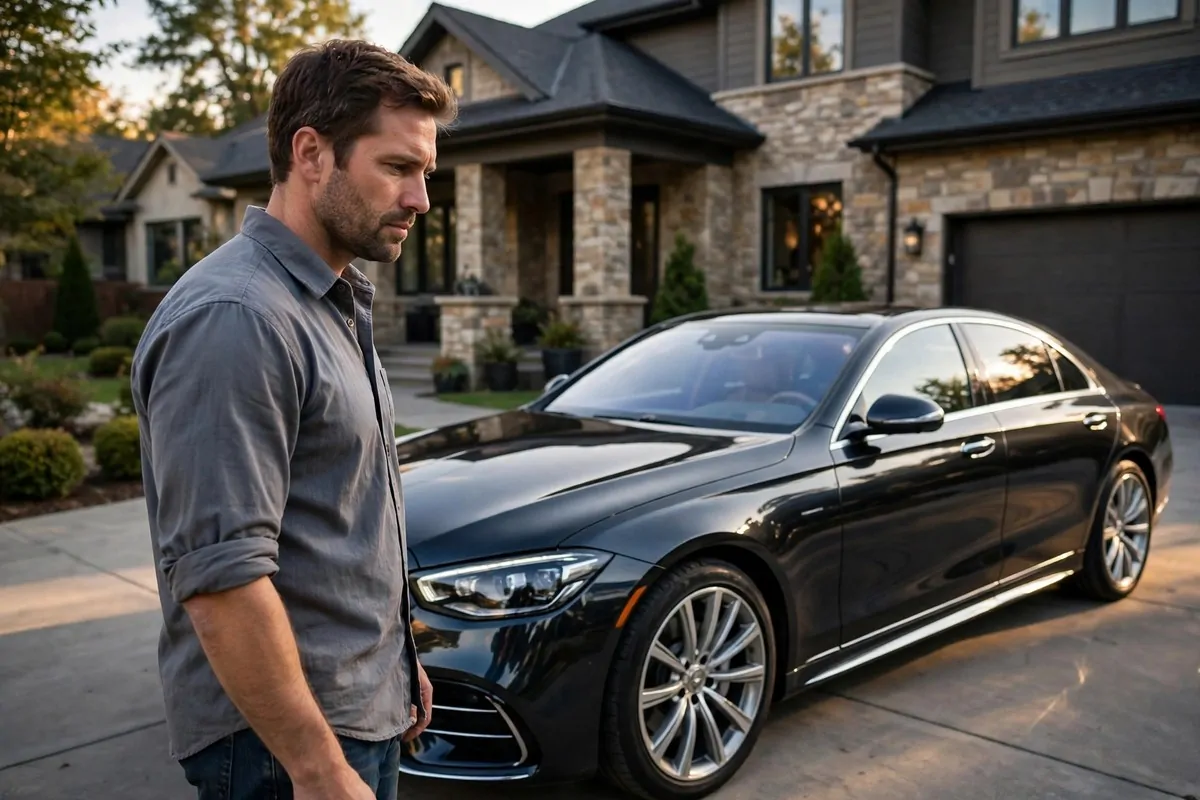
Well, a neighbour of mine once bought a costly car, and he washed it each Sunday with pride. He called the car his asset, and he told every guest that it was the best buy of his life. Yet each month the car took money from his pay for fuel, care, and fixes, and it gave nothing back but a shine. He owned the car, yet the car owned his pay, and that is the trap this article will help you see.
An asset is a simple thing to test, and the test fits in one plain sentence. An asset puts money in your pocket, and a liability takes money out of it. Robert Kiyosaki wrote this plain rule in his book Rich Dad Poor Dad, and the rule has guided millions of working people since. A thing that takes money from you each month is not an asset, even if the whole street calls it one.
I once met a driver who saved for years to buy a large house, and he called the house his wealth. The house took money each month for heat, care, and fixes, and the rooms sat empty while the pay ran thin. He was not a foolish man, and he simply trusted a word the street had taught him. The word was asset, and the house did not fit the word, yet no one had ever shown him the test.
The United States Small Business Administration reports that only about half of new small firms are still open after five years. Car pricing guides report that a new car can lose around 20 percent of its value in its first year. Home experts often say you should plan to spend about 1 percent of a home’s value each year on care and fixes. These numbers show that many things people call assets are really costs in disguise, and the disguise is what this article will lift.
Read the five things slowly, and test each one against the plain rule in your own life. The things the working class thinks are assets but are liabilities hide in plain sight, in driveways, in large homes, and in bright shops. Each one looks like wealth, yet each one quietly drains the pay that could build real wealth. When you learn to see the drain, you can stop it, and the saved pay can start to work for you.
The short answer: the things the working class thinks are assets but are liabilities are five common traps, from a costly car to a shop with no buyers. Each one looks like wealth, yet each one takes money from your pay each month and gives little back. When you test each thing with the plain rule, an asset puts money in your pocket and a liability takes it out, you can see the trap clearly and keep your pay for real wealth.
Key Takeaways
- A costly car takes money each month and loses value fast.
- A house too large for the pay drains money on upkeep.
- A small shop with no buyers is a cost, not wealth.
- A costly course that promises quick riches teaches little.
- Showy jewellery loses much of its price when sold.
1. The Costly Car That Eats Your Pay
The first trap is the costly car, and it is the trap most working people know by heart. A bright car in the driveway feels like proof of success, and neighbours nod when they see it shine. Yet the car takes money each month for fuel, care, fixes, and insurance, and the sum can eat a large share of the pay. A car that takes more than it gives is not an asset, and it is a liability with a bright coat of paint.
A new car loses value fast, and the loss starts the day it leaves the shop. Car pricing guides report that a new car can lose around 20 percent of its value in its first year, and the fall goes on for years after. A car bought for 30,000 dollars can be worth far less in five years, while the monthly cost goes on as if the value had stayed. The shine fades, yet the cost stays, and that gap is the trap.
The working class loves the car because the street can see it, and the street is a poor judge of wealth. A neighbour sees the shine and calls the owner rich, yet the owner knows the truth at the end of each month. A rich person buys a car for its use, and a working person often buys a car for its shine. The shine is bought with the pay, and the pay is the very thing that could build real wealth.
Test the car with the plain rule, and let the numbers speak. Write down what the car costs each month, from fuel to fixes, and write down what it gives back in money. A car that takes 400 dollars a month and gives back nothing is a liability of 400 dollars a month. A car that takes 150 dollars a month and does the same work is a smaller liability, and the saved 250 dollars can start a real pile.
Buy a car for its use, not for its shine, and keep the choice small and plain. A safe car that runs well for years is worth more than a bright car that breaks and drains the pay. A plain car bought with care can serve a family for a decade, and the saved pay can grow into real wealth. The car is a tool for work and family, and a tool is judged by its use, not by its shine.
Teach your children this test, so the trap ends with you. A child who learns that a car is judged by its cost, not by its shine, will grow into an adult who keeps his pay. The dinner table is the best school for money sense, and a family that tests its buys together grows rich together. A child who sees a plain car with pride will not need a bright car to feel rich.
Look at your own car tonight, and test it with the plain rule. If the car takes more from your pay than it gives back in use, the things the working class thinks are assets but are liabilities are at work in your own driveway. A smaller car and a growing pile beat a bright car and an empty purse, and the choice is yours to make. The first trap is the most common of the five, and it is also the easiest to escape.
2. The House That Is Far Too Large
The second trap is a house that is far too large for the pay that keeps it, and it wears the name of wealth with pride. A large house with many rooms feels like a grand win, and guests praise the space when they visit. Yet each room must be heated, cleaned, and fixed, and the cost grows with every extra wall. A house that takes more than it gives is not an asset, and it is a liability with a fine front door.
Home experts often say you should plan to spend about 1 percent of a home’s value each year on care and fixes. A home worth 200,000 dollars can ask for about 2,000 dollars a year in care, and the sum grows when the home is large. A leaking roof, a broken heater, and a cracked wall all wait for the owner, and each one takes from the pay. A large home is a large mouth, and the mouth must be fed each month.
A home can be a true asset when it fits the pay and serves the family well. A small home that is owned and cared for gives calm, pride, and a base for the children to grow. The trap is not the home itself, and it is the size that the pay cannot carry. A home that fits is a base, and a home that is too large is a weight.
The street praises large homes, yet the street does not pay the bills. A neighbour sees the wide rooms and calls the owner rich, yet the owner feels the truth each month when the pay runs thin. A wise person buys a home for its use, and a working person often buys a home for its size. The size is bought with the pay, and the pay is the very thing that could build real wealth.
Test the home with the plain rule, and let the numbers speak. Write down what the home costs each month, from heat to fixes, and write down what it gives back in money. A home that takes 1,000 dollars a month and gives back nothing is a liability of 1,000 dollars a month. A smaller home that takes 500 dollars a month does the same work for the family, and the saved 500 dollars can start a real pile.
Choose a home that fits your pay, and let the extra rooms go to someone else. A home with rooms the family truly uses is worth more than a home with rooms that sit empty. A plain home kept with care can serve a family for a lifetime, and the saved pay can grow into real wealth. The home is a base for life, and a base is judged by its calm, not by its size.
Look at your own home tonight, and count the rooms that sit empty each week. If the count is two or more, this trap may be yours to work on, and the work starts with an honest test. A smaller home and a growing pile beat a large home and an empty purse, and the choice is yours to make. The second trap is the quietest of the five, and it is also the one that drains the most over a lifetime.
3. The Small Shop With No Buyers
The third trap is a small shop or side trade started without real buyers, and it wears the proud name of business. A person opens a small shop, buys goods to sell, and tells friends that he now owns a business. Yet the goods sit on the shelf, the buyers never come, and the shop takes money each month for rent, stock, and light. A shop with no buyers is not an asset, and it is a liability with a bright sign above the door.
The United States Small Business Administration reports that only about half of new small firms are still open after five years. The firms that close are not always run by foolish people, and many of them simply started without enough buyers. A shop that opens before the buyers are found is a shop that pays for an empty room. The lesson is plain, and it is to find the buyers before you buy the goods.
A true business is an asset when it gives back more than it takes each month. A small trade with steady buyers can add a real sum to the pay, and the sum can grow into real wealth. The trap is not the trade itself, and it is the rush to open before the buyers are known. A trade with buyers is a stream, and a trade without buyers is a drain.
The street praises the shop owner, yet the street does not pay the rent. A neighbour sees the bright sign and calls the owner a boss, yet the owner feels the truth each month when the pay runs thin. A wise person starts a trade with a few buyers already in hand, and a working person often starts with hope alone. Hope is a fine thing, yet hope is not a buyer, and a shop needs buyers to live.
Test the shop with the plain rule, and let the numbers speak. Write down what the shop costs each month, from rent to stock, and write down what it brings in from buyers. A shop that takes 600 dollars a month and brings in 200 dollars is a liability of 400 dollars a month. A trade that brings in more than it takes is an asset, and the test is plain for any person to use.
Start small, and let the buyers come before the shop grows. A few goods sold from home can test the trade without the cost of a bright shop. A trade that grows from real buyers is a trade that lasts, and a trade that grows from hope alone fades fast. The shop is a tool for income, and a tool is judged by what it brings in, not by how bright its sign is.
Look at your own side trade tonight, and test it with the plain rule. If the trade takes more from your pay than it brings in, this trap may be yours to work on, and the work starts with finding buyers first. A small trade with real buyers beats a bright shop with empty shelves, and the choice is yours to make. The third trap is the proudest of the five, and it is also the one that teaches the hardest lesson.
4. The Costly Course That Promises Quick Riches
I once knew a young man who paid a large sum for a course that promised quick riches, and he showed me the bright papers with pride. The course taught him little, the promises faded in a week, and the large sum never came back. He called the course his asset, yet it took money from his pay and gave him no new skill. A course that takes money and teaches little is not an asset, and it is a liability with a bright promise.
Learning is a true asset when it brings a new skill that earns more pay. A night class that teaches a real trade can lift a worker for life, and the pay rise it brings is the proof. The trap is not learning itself, and it is the bright promise of quick riches with no real skill inside. A course that teaches a real skill is a seed, and a course that sells a dream is a drain.
The sellers of quick riches know the working class well, and they sell hope in bright words. They show rich cars, large homes, and smiling faces, and they ask for a large sum to share the secret. Yet the secret is often plain advice that costs nothing, and the large sum buys only bright words. A person who pays for a dream is a person who has bought a cost, not an asset.
Test the course with the plain rule, and let the numbers speak. Write down what the course costs, and write down what new skill it truly teaches. A course that costs 2,000 dollars and teaches no skill that earns pay is a liability of 2,000 dollars. A night class that costs 200 dollars and teaches a trade that earns more is an asset, and the test is plain for any person to use.
Ask three plain questions before you pay for any course, and let the answers guide your hand. Ask what real skill the course teaches, ask who has earned more pay with that skill, and ask if the same skill can be learned for free at a library. A course that answers all three with plain proof is worth its price, and a course that hides behind bright words is not. The questions are free, and they can save a large sum.
Teach your children this test, so the trap ends with you. A child who learns to ask for proof before he pays will grow into an adult who keeps his pay. The dinner table is the best school for money sense, and a family that tests its courses together grows wise together. A child who sees a parent ask hard questions will learn to ask them too, and the habit will guard him for life.
Look at the last course you paid for, and test it with the plain rule. If the course took more from your pay than it gave back in skill, this trap may be yours to work on, and the work starts with three plain questions. A real skill and a growing pile beat a bright promise and an empty purse, and the choice is yours to make. The fourth trap is the brightest of the five, and it is also the one that preys on hope itself.
5. The Showy Jewellery That Loses Its Price
I once watched a neighbour buy a costly gold chain to show at a wedding, and he called it his wealth. He wore it once, kept it in a box for years, and sold it one hard month for far less than he had paid. He called the chain his asset, yet it took money from his pay and gave back only a shine. A showy piece that loses its price when sold is not an asset, and it is a liability that hangs around the neck.
Jewellery bought to show is priced for the shop, not for the buyer, and the price falls the moment it leaves the shop. The shop adds a large sum for its craft and its shine, and the buyer pays that sum with pride. When the piece is sold, the buyer learns that the shop price has vanished, and the loss can be half the sum he paid. A piece bought for show is a cost, and a piece bought for true worth is a different thing.
The test for jewellery is the same plain rule, and it fits in one short question. Ask what the piece would bring if it were sold today, and compare that sum with the price that was paid. A piece that brings back most of its price is a fair store of worth, and a piece that brings back half is a cost in disguise. The question is free, and it can save a large sum before the buy.
| Thing people call an asset | What it costs each year | What it gives back |
|---|---|---|
| Costly car | Fuel, care, and fixes each month | A ride to work, and little else |
| House too large | Heat, care, and fixes each month | Rooms that sit empty |
| Small shop, no buyers | Rent, stock, and light each month | Few sales, and worry |
| Costly course | A large sum paid at once | Bright words, and little skill |
| Showy jewellery | A large sum paid at once | Half its price when sold |
The street praises showy gold, yet the street does not pay the price. A neighbour sees the shine and calls the owner rich, yet the owner knows the truth at the end of each month. A wise person buys jewellery for its true worth, and a working person often buys it for its shine. The shine is bought with the pay, and the pay is the very thing that could build real wealth.
Buy jewellery for its true worth, not for its shine, and keep the choice small and plain. A plain piece bought with care can hold most of its worth for years, and the saved pay can grow into real wealth. A showy piece bought for a wedding fades in a box, and the money it took is gone for good. The piece is judged by what it brings back, not by how bright it shines.
Teach your children this test, so the trap ends with you. A child who learns that a piece is judged by its sale price, not by its shine, will grow into an adult who keeps his pay. The dinner table is the best school for money sense, and a family that tests its buys together grows rich together. A child who sees a plain choice with pride will not need a showy piece to feel rich.
Look at your own jewellery tonight, and test it with the plain rule. If the piece would bring back far less than it cost, the things the working class thinks are assets but are liabilities are at work in your own box. A plain piece and a growing pile beat a showy chain and an empty purse, and the choice is yours to make. The fifth trap is the shiniest of the five, and it is also the easiest to see once the test is known.
Conclusion
These five traps share one plain idea, and that idea is that a name does not make an asset. The things the working class thinks are assets but are liabilities hide in driveways, in large homes, in bright shops, in costly courses, and in showy chains. Each one looks like wealth, yet each one quietly drains the pay that could build real wealth. A plain test can lift the disguise, and the test fits in one short sentence.
Kiyosaki showed by his plain rule that wealth is built by keeping what an asset gives and cutting what a liability takes. An asset puts money in your pocket, and a liability takes money out of it, and the rule never lies. His way asks for no large sum and no rare gift, and it asks only for an honest look at each thing you own. An honest look kept each month is a habit, and a habit kept for a year is a new life.
I hope you test your own five things tonight, and mark each one with an honest hand. You may hold two or three already, and that is a fair start for any working family. Pick the weakest trap first, and give it one small step this week. A single test, a single smaller choice, or a single saved sum can start the change.
Your past does not decide your future, and your wage does not decide it either. Your daily choices decide it, one small test at a time, and each test is a brick in a new life. A family that keeps its tests in calm is a family that climbs, and the climb is real even when it is slow. The climb starts with seeing, and seeing starts tonight.
Share this article with a friend who works hard yet wonders where his pay goes each month. A shared test is easier to use than a lonely one, and a friend who tests his five things with you grows with you. Talk about the five traps at the dinner table, and let each person name the one they see most. A table shared in honesty is a table that grows rich.
A year from now, the traps will be weaker, and the real assets will feel more like home. Keep the test, keep the plain choices, and keep the calm that a growing pile brings. Wealth is not a single leap, and it is a slow climb that rewards each steady foot. The pile you build today will guard your family for years to come.
Tonight, before the day ends, take one small step that proves the change is real. Test one thing you own, write down what it costs each month, or ask three plain questions before your next large buy. A year from today, you will be glad you started on this very night. Real wealth is not far away, and it is one honest test closer with each day you practice.