10 Habits of People Who Thrive in Any Economy (Good or Bad)
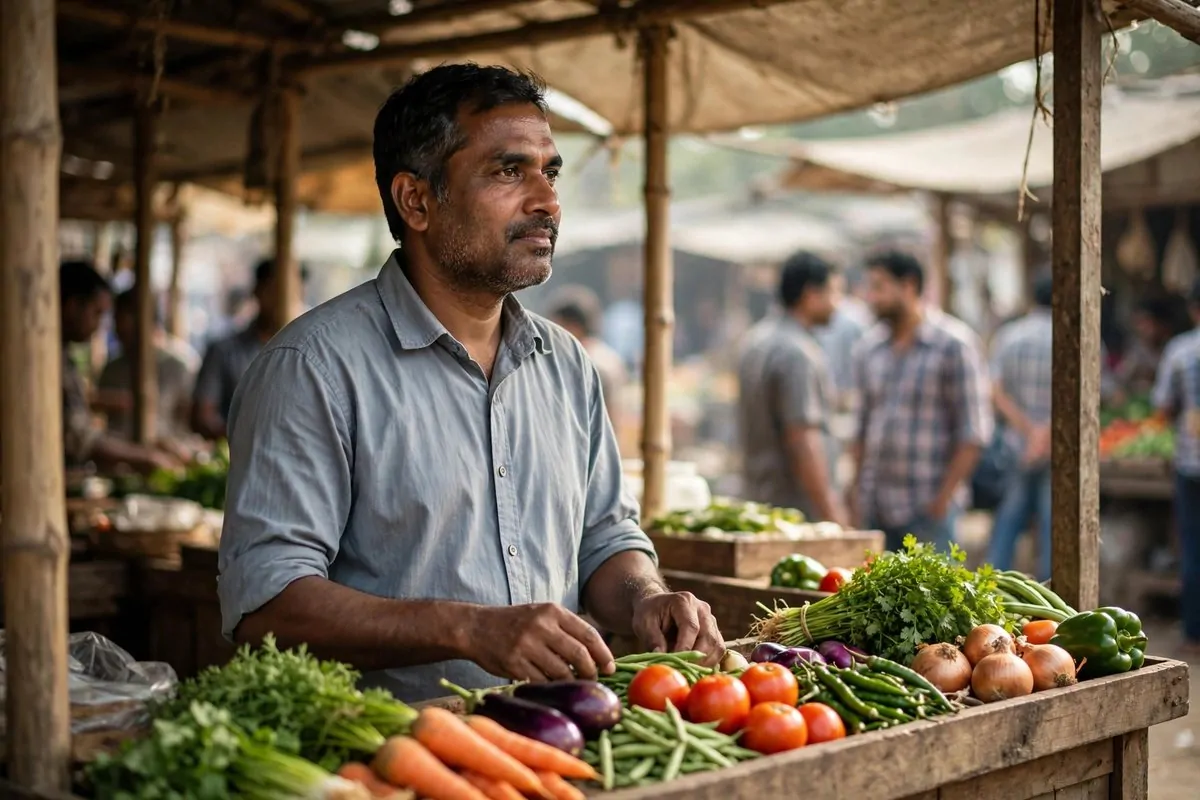
Picture this, two shop owners on the same street. When slow months come, one shuts his doors while the other stays open and even grows a little. The difference between them was not luck. It was habit.
Every economy moves in rounds. Good years make money feel easy, and then slow years test everyone. The same street looks very different in each round.
Most people change how they act with each round. They spend big when money flows and freeze when it stops. People who thrive keep the same steady habits in both rounds.
That is what this article is about. You will learn ten habits that work when money is easy and when money is tight. Each habit is shown from both sides, so you can see how it helps in a boom and in a bust. Every habit is plain, and you can start most of them this week.
You do not need a high income to use them. You only need the will to start small and stay steady.
The short answer: Labor data shows that job losses rise in every downturn, and bank surveys keep finding that many working adults could not cover a surprise bill from cash set aside. People with low fixed costs, a cash cushion, and more than one income source handle those shocks far better. The ten habits below build exactly that kind of safety, and they pay off in good times too.
Key Takeaways
- Keep fixed costs low so a pay cut hurts less.
- Hold more than one income source so one can cover for the other.
- Keep learning a paid skill so your work stays in demand.
- Keep cash set aside for hard months so shocks stay small.
- Avoid tying your life to big fixed spending you cannot drop.
- In tough times, spend on skills first and on new things last.
- Stay employable with a clean record and fresh skills.
- Keep a small side project warm so it is ready when you need it.
- Help your network now, before you ever need help back.
- Review your money once a month and fix small leaks fast.
1. Keep Your Fixed Costs Low
Fixed costs are the bills you must pay every month no matter what. Rent, a phone plan, and transport passes are fixed costs. Food and fun spending can shrink, but fixed costs stay the same.
Ali is a driver for a small firm. He earns 3,000 a month in good times. His fixed costs are 1,800, which leaves him room to save. When his hours were cut last year, his pay fell to 1,500.
His bills did not fall with his pay. He still owed 1,800 every month. That gap is what breaks most people in a downturn.
Now picture Ali with fixed costs of only 900. The same pay cut would still hurt. But 1,500 of pay against 900 of bills leaves room to breathe. That is the whole power of this habit.
| High fixed costs | Low fixed costs |
|---|---|
| Monthly bills of $1,800 | Monthly bills of $900 |
| Pay drops to $1,500, but $1,800 is still owed | Pay drops to $1,500, but only $900 is owed |
| Short $300 every month | $600 left to live on |
In good times this habit looks boring. Friends may spend more while you keep your flat small and your plans plain. But your extra pay turns into savings instead of bigger bills.
In bad times this habit looks like genius. Your bills stay low while others drown in theirs. You sleep better, you think clearer, and you get more time to fix the problem. Low fixed costs buy you time, and time is what solves most money problems.
Start by listing every bill that repeats each month. Ask which ones you could shrink or drop. Cut one this week, and your future self will thank you.
2. Keep More Than One Income Source
One income is one point of failure. If it stops, everything stops with it. A second income does not need to be big. It only needs to be alive.
Mina sells vegetables at a morning stall. On weekends she also packs veg boxes and delivers them to homes nearby. Her stall is her main income, and the boxes are her second.
In good times both streams grow. More buyers visit the stall, and more families order boxes. Mina saves the extra instead of spending it. Her two incomes make good months even better.
In bad times foot traffic at the stall drops hard. Fewer buyers walk by, and her stall income falls by half. But the delivery boxes hold steady, because families still need food at home.
That second stream kept her rent paid through the whole slow season. It was not big enough to make her rich. It was big enough to keep her calm. Calm people make better choices than scared people.
You can build a second stream with skills you already have. Start with a few hours a week and let it grow slowly.
Do not wait for trouble to start one. A second income built in good times is a lifeboat ready in bad times. Start yours this month, even if it is tiny.
3. Keep Learning a Paid Skill
A paid skill is any skill people will pay you for. Repair work, cooking, driving, sewing, and writing are all paid skills. The more current your skill, the safer your income.
Omar fixes mobile phones from a small shop. Two years ago he spent three weekends learning to fix laptop screens too. The course cost him little, and he practiced on old broken laptops. Now he offers both services from the same shop.
In good times his new skill brings richer jobs. Laptop repairs pay more than phone repairs. His income rose without longer hours.
In bad times his skill mix saves him. People stop buying new phones, but they repair old ones more. His shop stays busy while sellers of new phones sit idle. Learning kept him on the right side of the downturn.
I once met a repair man who learned one new skill every single year. He told me each new skill was like adding another leg to a table. A table with four legs does not fall when one leg breaks.
You do not need costly courses. Free videos, a patient mentor, or practice on old items can teach a lot. Pick one skill close to what you already do. Learn it a little each week until it can earn.
Skills do not rot like stock and cannot be taken like a job. They travel with you into every economy.
4. Keep a Cash Cushion for Hard Months
A cash cushion is money set aside for hard months. It is not for fun and not for plans. It sits waiting, like a spare tire in a car. You hope you never need it, but you drive calmer knowing it is there.
Laila cooks food at home and sells it to workers nearby. Every week she puts a small part of her earnings in a jar. Some weeks it is only a little, but she never skips.
In good times her jar fills faster. Festival weeks bring more orders and bigger savings. She watches the jar grow and feels proud. That pride keeps her going in slow weeks.
In bad times the jar earns its keep. When her child fell sick, she paid the clinic from the jar. She did not panic, and she did not have to stop her work.
| Month | Saved that month | Cash set aside so far |
|---|---|---|
| Month 1 | $40 | $40 |
| Month 2 | $40 | $80 |
| Month 3 | $50 | $130 |
People without a cushion face the same shock very differently. A single bad week can force choices they hate. Laila’s jar turned a crisis into a bad day. That is all a cushion needs to do.
Start with any amount you will not miss. Small and steady beats big and rare.
Keep the cushion where you can reach it but will not touch it daily. A jar, an envelope, or a separate account all work. Add to it first when money comes in, not last.
5. Avoid Lifestyle Lock-In
Lifestyle lock-in means tying your life to big fixed spending. A bigger flat, a new car, and costly habits lock you in. They feel great until income drops, and then they own you.
Imran is a tailor with a small shop and steady hands. In his best year he could have moved to a bigger flat and bought a new car. He stayed in his small flat and kept his old scooter. His friends called him too careful.
In good times lock-in looks like success. His friend took the big flat and the new car and posted photos. Imran looked plain next to him, but his money stayed free.
In bad times the story flips. Orders fell for three months, and Imran’s small bills were easy to cover. His friend still owed big money every month with half the income. Freedom beat appearances.
Lock-in is quiet because each upgrade feels small. One bigger bill at a time, until your whole pay is spoken for. The habit is to pause before every upgrade and ask one question.
Ask whether you could still pay for it if your income fell by half. If the answer is no, wait. Waiting is not losing. It is choosing freedom over show.
Live a little below what you earn, in every season. Your future self will thank you for the room to breathe.
6. Buy Skills, Not Stuff, When Times Are Tough
Tough times tempt people to buy comfort. A new phone or new clothes can feel like a fix. But things lose value fast, and they never raise your income. Skills do the opposite.
Tariq drives a taxi in a busy city. When ride demand fell, his daily earnings dropped hard. He felt the pull to buy small comforts to feel better.
Instead he spent a small sum on an English phrase course for drivers. He learned how to greet tourists and explain routes clearly. His tips rose within weeks. The course paid for itself many times over.
In good times he follows the same rule. When earnings are high, he takes a defensive driving course instead of eyeing a fancier car. Better skills bring better ratings, and better ratings bring more rides.
In bad times this habit turns defense into attack. While others cut all spending and wait, Tariq invests tiny sums in himself. Each new skill opens a door that was closed before. He moves forward while the market moves back.
Before any purchase in a slow month, ask what it earns you. If the answer is nothing, put the money toward a skill.
Things break, fade, and go out of style. Skills stay in your hands for life. In every economy, the best asset you can buy is a better you.
7. Stay Employable
Employable means easy to hire and hard to let go. It rests on two legs: a clean work record and fresh skills. Lose either leg and you wobble.
Sara works in the front office of a trading firm. She arrives on time, keeps her word, and never gossips about colleagues. When new software arrived, she learned it before anyone asked. Her manager noticed all of it.
In good times her record brings rewards. She was picked for the new project and then for a raise. Being reliable made her visible in the best way.
In bad times her record protects her. When the firm cut staff, her name stayed off the list. Managers keep the people they trust most. Trust is built in good times and spent in bad times.
Even if she had lost that job, her record would travel with her. Old bosses give strong references to steady workers. A clean name opens doors faster than any certificate.
You build this daily, not yearly. Show up on time, finish what you start, and learn the next tool before it is required. Small acts of care stack into a name people trust. That name is your real job security.
Jobs come and go, but a strong name follows you. Guard it like cash.
8. Keep a Small Side Project Warm
A side project is small work you do beside your main job. It stays warm when you give it a few hours each week. A warm project can grow fast when you need it. A cold one takes months to restart.
Kamran is a clerk at a warehouse. Three evenings a week he writes short product descriptions for online sellers. It started as tiny gigs for little pay.
In good times the project is pocket money. His clerk pay covers the bills, and the gig money goes to savings. He keeps his clients happy with fast replies. Slow and steady, his client list grows.
In bad times the project turns into a bridge. When his warehouse cut everyone’s hours, his pay fell sharply. He told his clients he had more time, and the gigs doubled.
The bridge carried him over four hard months. He never missed rent, and he never panicked. When full hours returned, he kept the project warm again. He learned that warm beats big.
Pick something simple that fits your skills. A few ideas that work for many people are listed below. Start with one, and give it two hours a week.
- Help neighbors with small repairs or sewing fixes on weekends.
- Cook one extra dish and sell portions to workers nearby.
- Offer simple writing, typing, or delivery help online.
Two hours a week is enough to keep it warm. Warmth today is income tomorrow.
9. Help Your Network Before You Need It
Your network is the people who know you and trust you. Friends, past colleagues, neighbors, and happy customers all count. A strong network is built long before you need it.
Nadia teaches at a small school. She shares job posts she sees, connects people who can help each other, and checks on old colleagues. She asks for nothing in return. Helping is simply her habit.
In good times her network keeps growing. Each person she helps remembers her kindness. Her circle widens year by year without any effort to impress.
In bad times the circle pays her back. When her school cut teaching hours, her pay dropped at once. Within a week, three people sent her tutoring leads. She filled her empty hours within a month.
I have seen this pattern work more than once. Givers collect goodwill the way savers collect cash. When trouble comes, that goodwill spends well.
Start where you are. Share a useful post, make one introduction, or praise someone’s work in public. Do it weekly until it feels natural. Never keep score, because scorekeeping kills the habit.
Help first, help often, and help without a plan. Your network will remember.
10. Review Your Money Once a Month
Money leaks are small and silent. A forgotten subscription or daily snack adds up fast. A monthly review catches leaks while they are small. One hour a month can save hundreds a year.
Farhan drives a bus on a fixed route. On the first Sunday of each month he sits with tea and a small notebook. He writes what came in and what went out.
In good times his review finds waste. Last spring he found two subscriptions he never used. He cut them and sent the savings to his cushion. Good months got even better with one small fix.
In bad times his review finds danger early. When fuel costs rose, he saw his transport spending jump at once. He packed lunch instead of buying it and closed the gap fast.
Without the review, both leaks would have run for months. Small leaks sink big ships, as sailors say. Farhan’s notebook is his early warning system. An hour of honesty beats a year of guessing.
Keep the review simple so you will actually do it. Four short steps are enough, and they are listed below. Same day each month, no skipping.
- Write down all money that came in.
- Write down all money that went out.
- Check your cash set aside and add a little.
- Pick one small fix for next month.
What gets reviewed gets better. Start this Sunday and watch your money calm down.
Conclusion
Economies will keep moving in rounds, and no habit can stop that. But habits decide how each round treats you. The ten above work in good times and bad because they build the same thing: room to breathe.
I believe steady habits beat big plans. You do not need to master all ten this week. Pick two, start them small, and let them grow with you.
When the next slow season comes, and it will, you will be ready. Low bills, a second income, and cash set aside turn fear into a plan. That calm is worth more than any raise.
Start today with one small step. Your future self is counting on you.